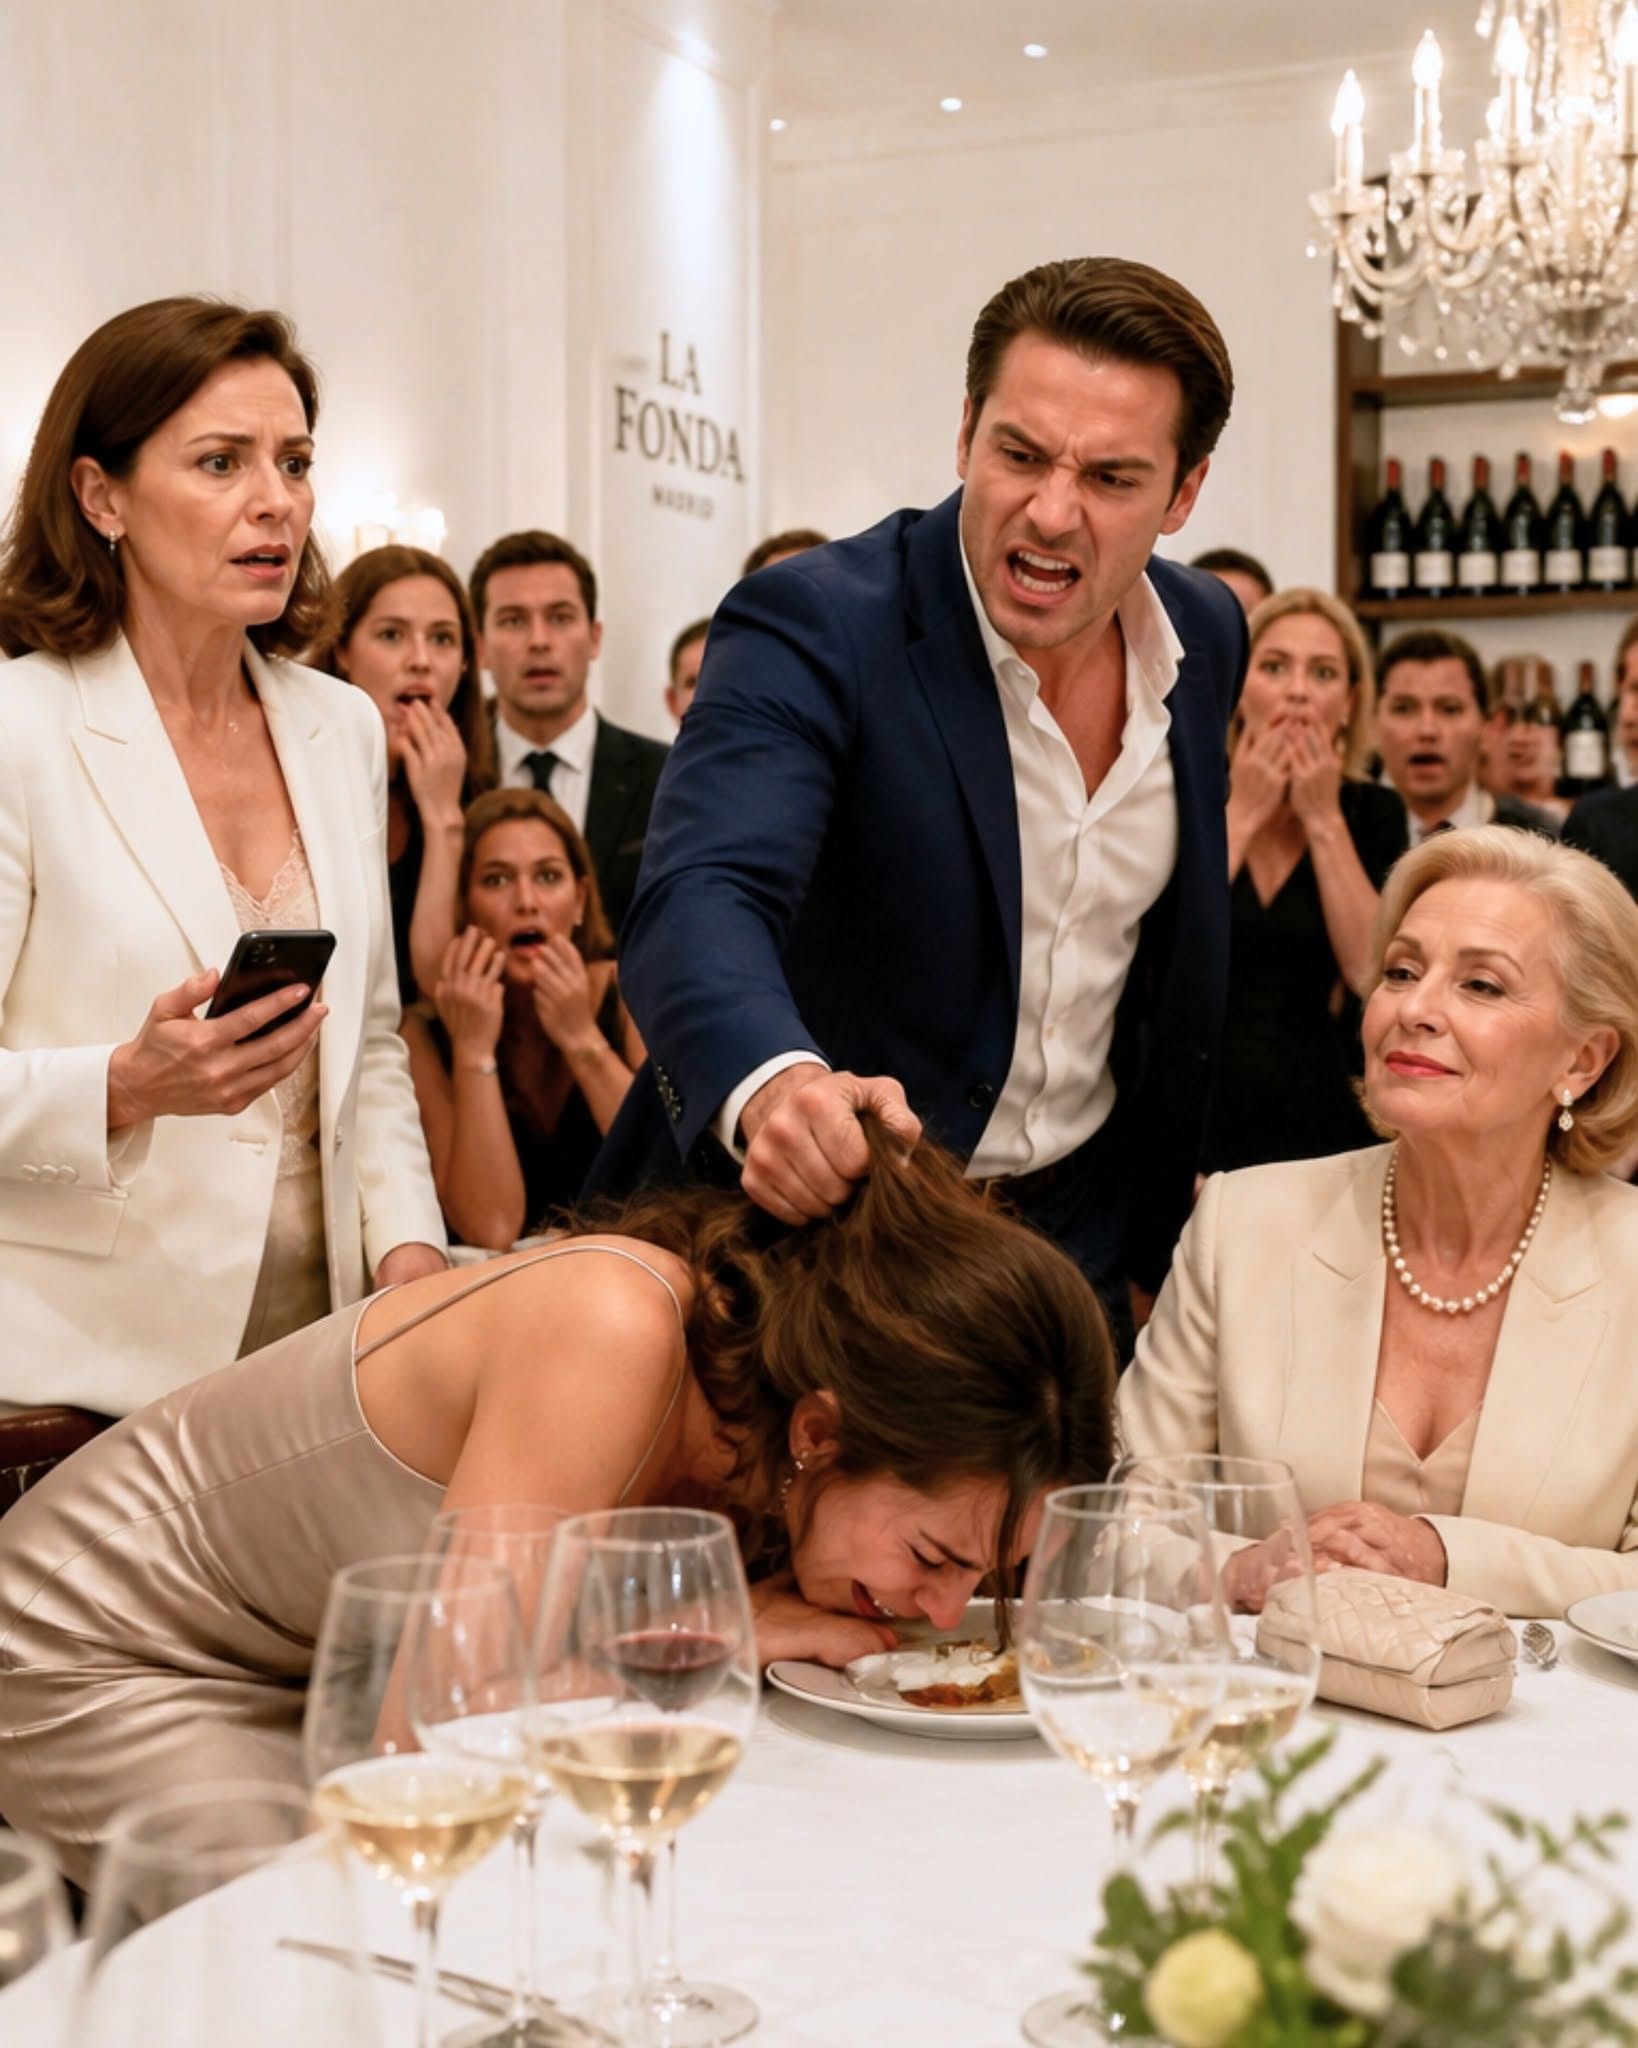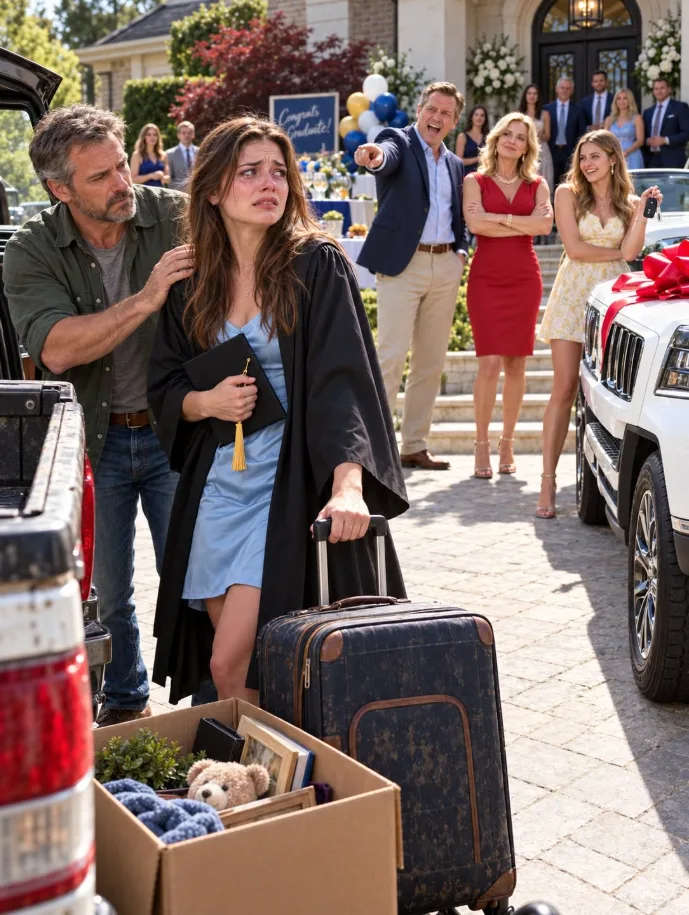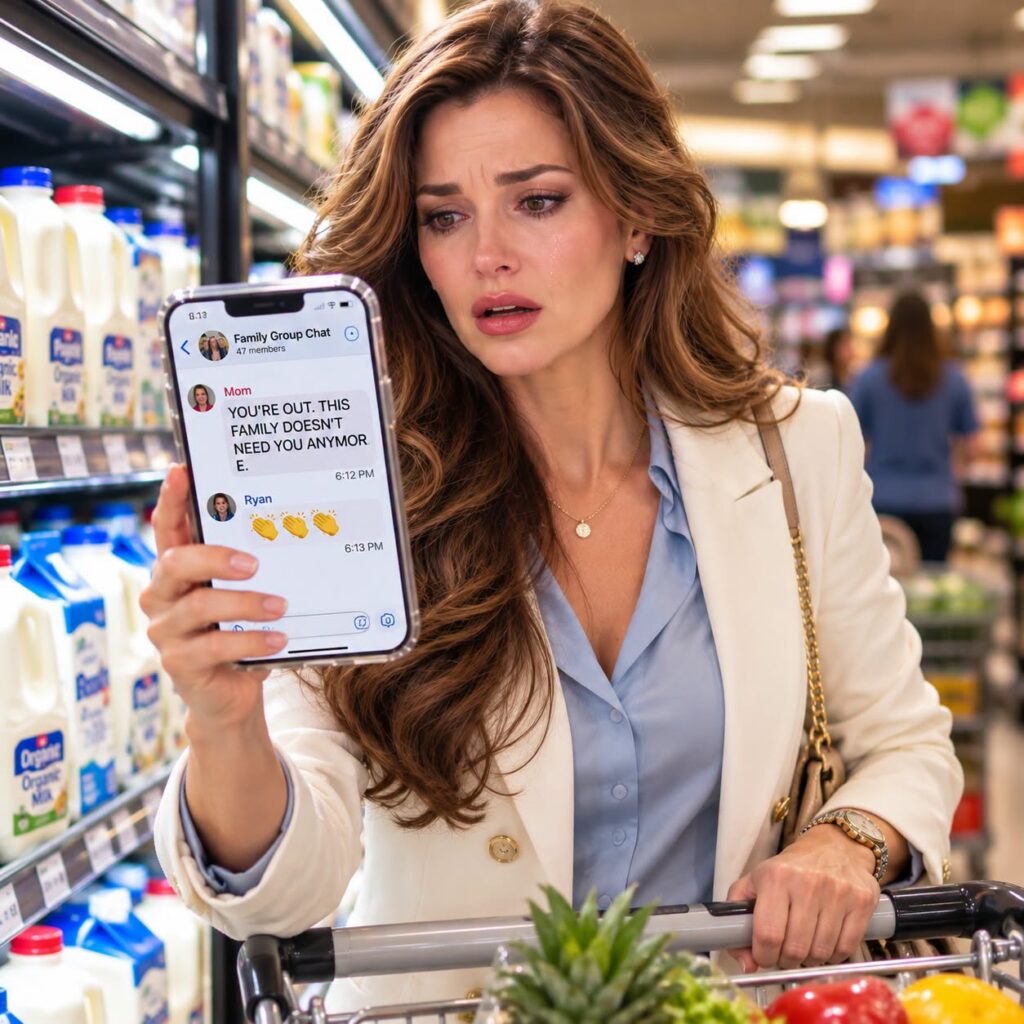
At 6:12 p.m., my mother announced to forty-seven relatives that I was no longer part of our family.
“YOU’RE OUT. THIS FAMILY DOESN’T NEED YOU ANYMORE.”
My brother, Ryan, responded with three clapping emojis.
I was standing in a Raleigh grocery store, holding a carton of milk, when my phone lit up. I read the message twice. Then I set the milk back before my shaking hands dropped it.
For seven years, I had paid the bills that kept my parents’ lives running. Their $2,640 mortgage. Dad’s restaurant insurance. Ryan’s delivery-truck lease. Even the restaurant’s commercial freezer. The automatic payments came from my checking account, not some magical family fund.
Every month, $9,870 disappeared before I bought anything for myself. My own roof leaked whenever it rained, and I had postponed a dental crown for six months. Meanwhile, Mom had just leased a new Lexus.
I did it because Dad had suffered a stroke, and Mom promised it would only be until the restaurant recovered. Then Dad recovered. The restaurant didn’t. Somehow, my temporary help became their permanent entitlement.
The fight started that afternoon when Ryan slid a loan application across my parents’ kitchen table.
“Six hundred and eighty thousand,” he said. “We’re opening a second location. You just have to guarantee it.”
I stared at the page. The proposed collateral included my house.
“No.”
Mom’s smile vanished. “After everything this family has done for you?”
“You mean everything I’ve done for this family?”
Dad slammed his fist against the table. “Don’t make your brother beg.”
I pushed the papers back. “I will help you speak to another lender. I will not put my home at risk.”
Ryan leaned close enough that I could smell his expensive cologne. “Then don’t expect to be invited when we make it big.”
I left before they could see me cry.
Now, in the grocery aisle, my phone buzzed again. Cousins reacted with shocked faces. My aunt typed, then deleted, a message. Nobody challenged my parents.
I opened my banking app. One by one, I canceled the scheduled future payments. Mortgage transfer. Truck lease. Freezer financing. Insurance premium. Nothing already paid was reversed. Nobody’s electricity would vanish tonight. They would simply have to cover their own next bills.
Then I typed into the family chat:
“PERFECT TIMING — I JUST CANCELED ALL THE PAYMENTS TOO…”
Ryan answered with a laughing emoji.
He stopped laughing ninety seconds later.
My phone began vibrating without a pause. By the two-minute mark, the call log showed 300 missed attempts. Most came from the restaurant’s customer-notification number, a system I’d helped Ryan install. Someone was using its automated dialer to flood my phone.
I switched on Do Not Disturb and walked toward the parking lot.
A voicemail slipped through from a number I didn’t recognize.
“This is Elena Brooks with the bank’s fraud review team. Ms. Cook, we urgently need to verify a personal guaranty submitted in your name today.”
I stopped beneath a flickering streetlight.
Then Elena added, “The application lists your house as collateral. The closing is scheduled for nine tomorrow morning.”
My parents had just thrown me out of the family. Somehow, three hours earlier, someone had signed me into a debt that could swallow my home. And the louder my phone rang, the clearer one thing became: they weren’t calling because they missed me.
“Do not approve anything,” I told Elena.
“We’ve placed the file on hold pending identity verification,” she said. “But I need you to come to the branch first thing tomorrow.”
I sat in my locked car and called Lydia Chen, the attorney who had helped me establish my bookkeeping business. She told me to preserve every message, dispute the application in writing, and freeze my credit with all three bureaus.
“Don’t confront them alone,” she warned. “People who forge paperwork can become desperate when it stops working.”
By midnight, Elena had sent a secure copy of the disputed documents after verifying my identity. I opened them beside a mug of untouched coffee.
There was my name beneath an electronic signature I had never made. An email address that looked almost like mine. A bank statement showing a balance I didn’t have. And a draft deed of trust that would have secured their loan against my house if I had actually authorized it.
The address was correct. The signature wasn’t.
The application claimed I was investing $118,000 in Ryan’s expansion. Lydia found the number buried in seven years of invoices: it was roughly what I’d spent covering their bills over the previous twelve months.
“They turned your support into supposed investment capital,” she said. “That doesn’t make you an investor.”
Then we reached the liabilities schedule.